

Commentary
While the EU and European governments are embracing the much-lauded middle-power moment, this entails three difficult conundrums.
Richard Youngs
{
  "authors": [
    "Vladyslav Rashkovan",
    "Gregory P. Wilson"
  ],
  "type": "commentary",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Europe"
  ],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Europe",
  "programAffiliation": "",
  "regions": [
    "Europe",
    "Ukraine"
  ],
  "topics": [
    "EU",
    "Foreign Policy"
  ]
}
Source: Getty
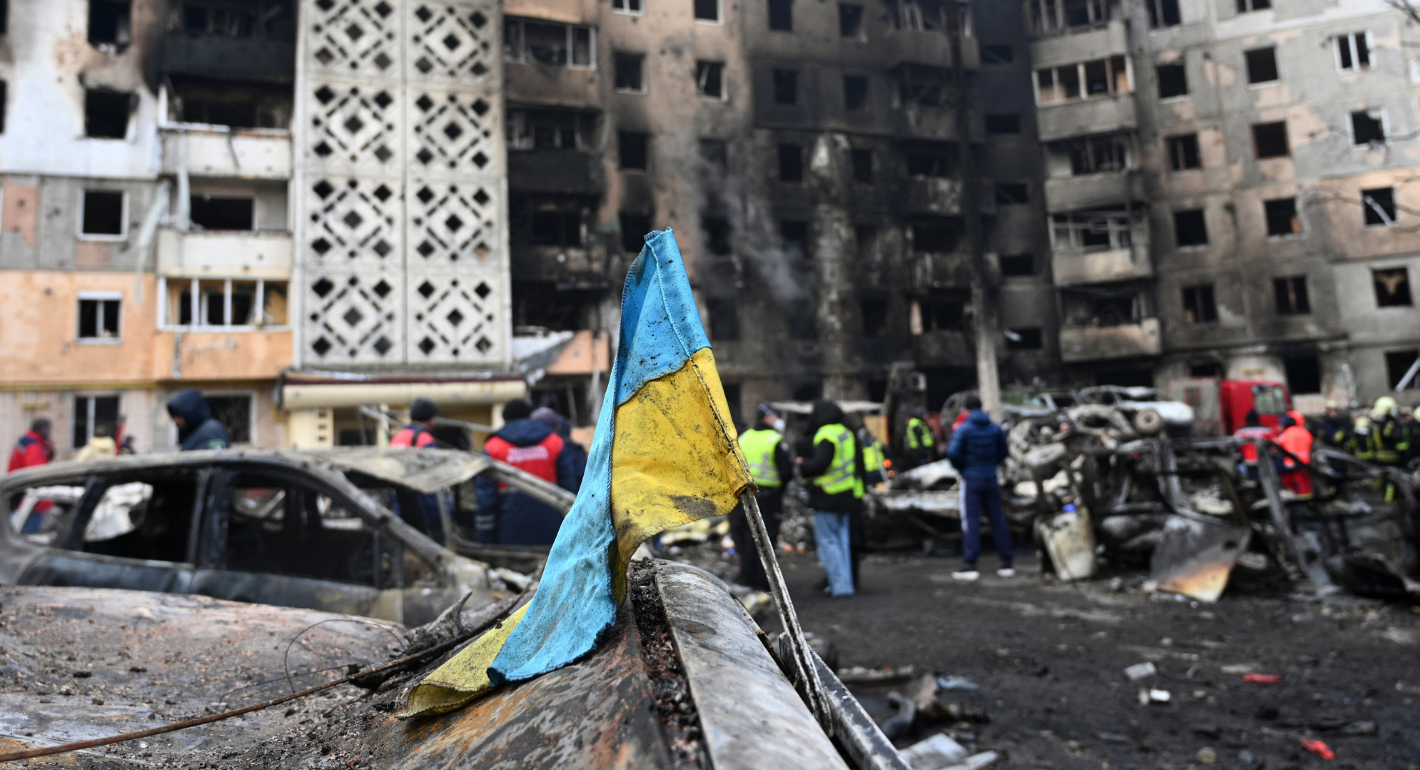
Funding Ukraine remains a priority for European leaders. As Russia’s war of aggression heads into another winter, two feasible options to mobilize support for Kyiv should be fast-tracked.
For nearly five years, as the killing, destruction, and costs of Russia’s full-scale war against Ukraine have mounted, the country’s Western partners have provided substantial financial support. Yet, existing commitments are unlikely to meet Ukraine’s near-term financing needs.
Ukraine’s partners should therefore consider two additional paths to help close the gap by using Russian sovereign assets immobilized in 2022 under EU sanctions.
There is no consensus in the EU on directly tapping into Russian assets, primarily because of the Belgian government’s concerns about the legal and financial exposure of Euroclear, the Belgium-based central securities depository where most of the assets are housed. As a result, the proposals below build on mechanisms already agreed on by the EU and the G7 to use the assets without formally touching the Euroclear accounts.
The most important precedent for this kind of support is the G7’s $50 billion Extraordinary Revenue Acceleration (ERA) loan, agreed on under Italy’s 2024 G7 presidency as part of the IMF financing program for Ukraine. The ERA loan was designed to be serviced by future flows of extraordinary revenues generated by the immobilized Russian assets. Most of these funds have already been disbursed to Ukraine.
A second important precedent came in December 2025, when the European Council approved a €90 billion ($101 billion) Ukraine Support Loan (USL). The first tranche was released to Ukraine in June 2026; by early October, Kyiv had received about €15.7 billion ($17.6 billion) under the scheme. The USL was a compromise after European leaders failed to agree on a proposed interest-free reparations loan of almost €140 billion ($157 billion) for Ukraine, despite calls from German Chancellor Friedrich Merz and other experts. That proposal ultimately floundered in part over how to share the legal and liquidity risks concentrated in Belgium and Euroclear.
Through the bipartisan REPO for Ukrainians Act, enacted in 2024, the United States also took action to authorize the use of Russian sovereign assets under U.S. jurisdiction. Bipartisan efforts to overcome the act’s delayed implementation followed in 2025, with two bills advancing through the Senate Foreign Relations Committee and the House Financial Services Committee, respectively. The proposed PEACE Act would mandate the accelerated transfer of these assets to Ukraine and authorize Kyiv to buy defensive weapons. But the funds are unlikely to reach Ukraine soon enough to make a material difference in time.
Further European discussions are also underway to transfer Russian funds held at Belgium’s Euroclear to a well-structured legal entity outside Belgium. While this idea may improve accountability, investment management, and protection against risks to Euroclear, it looks legally complex and does not answer the immediate question of how to provide Ukraine with additional funding now.
In November 2022, the UN General Assembly endorsed an international compensation mechanism for damage, loss, and injury caused by Russia’s wrongful acts. The Council of Europe established the Register of Damage as the mechanism’s first component in May 2023, followed by the International Claims Commission, set up in December 2025. But without a compensation fund, which is not yet established, and without clarity on further financing, the arrangement offers a path to important, much-needed redress in the long term—but not near-term financing.
With no immediate end in sight to Russia’s imperialist war, the ERA funds largely disbursed, and the USL covering only two-thirds of Ukraine’s economic needs through 2027, Ukraine will likely need tens of billions of euros more next year to defend its sovereignty and protect civilians. As an April 2026 report concluded, supporting Ukraine today is more cost effective than rearming Europe later. Immediate, coordinated G7 and European action is therefore required.
In December 2025, EU leaders decided to extend the immobilization of Russian central-bank assets indefinitely, barring them from being transferred back to Russia for as long as necessary. This decision replaced the previous six-month renewals, which required unanimity; now, it is impossible for a single EU member’s veto to unfreeze the assets. Similarly, under a 2024 U.S. law, Russian sovereign assets effectively cannot be sent back to Russia until hostilities cease and full compensation is paid for the damage caused to Ukraine.
With the political risk of continued immobilization now substantially reduced, there are two possible solutions. Another round of large-scale, direct taxpayer-funded grants from national governments may be politically difficult to secure amid contentious EU budget negotiations and elections next year in several key European countries. These proposals therefore seek to mobilize substantial financing for Ukraine while minimizing immediate taxpayer-funded expenditure and making greater use of European and G7 balance-sheet capacity, guarantees, and burden sharing.
One option is an ERA 2.0 loan, which could mobilize another €30–50 billion ($34–56 billion). Importantly, the repayment infrastructure already exists: The EU’s Ukraine Loan Cooperation Mechanism channels revenues generated by frozen Russian assets toward repayment of ERA loans. ERA 2.0 could strengthen its cash flows in three ways.
First, the EU and the G7 could extend the commitment of Russian-derived revenues to ERA 2.0 until the additional loans are repaid, and they could ensure any eventual release of Russian assets is paired with Russian reparations paying the outstanding ERA 2.0 balance. This would build on the more durable immobilization regime already in place.
Second, the G7 could bring additional, legally assignable extraordinary revenues from non-EU jurisdictions into the repayment pool.
Third, returns on the relevant cash balances could—where legally and operationally feasible—be protected with explicit guarantees or risk sharing for any additional market risk. ERA 2.0 should also be a fully non-recourse loan, meaning that any residual balance would be payable by Kyiv only from Russian reparations or an agreed-on G7 or EU backstop.
A larger Ukraine Support Loan, or USL 2.0, offers another viable path. Unlike the ERA, the USL’s size is not constrained by revenues from frozen Russian assets.
Raising the ceiling to €135–150 billion ($151–168 billion) would provide another €45–60 billion ($50–67 billion) through the same structure, with Ukraine repaying only when Russian reparations become available. The EU would maintain the right, consistent with EU and international law, to use Russian assets to repay the loan, although this would require lifting the statutory ceiling and the corresponding EU budget guarantee.
But who would carry the financing cost? Under the current USL, the EU covers the commission’s funding, liquidity-management, and related borrowing costs through a dedicated borrowing-cost subsidy, shielding Ukraine.
The existing framework allows third countries to contribute to these costs (indeed, the UK agreed to this in 2026). The same channel could be broadened into a G7-wide arrangement, with the EU providing the additional principal and guarantee while G7 partners cover some or all incremental financing costs.
Alternatively, the corresponding interest could be capitalized into the same limited-recourse claim and become payable only from future Russian compensation. This could reduce the need for an annual EU borrowing-cost subsidy, although the commission would still need to finance or refinance the cash interest on its own market borrowing in the interim.
Given that grants will help Ukraine more than loans, and provided that any capitalized interest remains subject to the same limited-recourse trigger as the principal, this structure should preserve the USL’s favorable treatment in the IMF’s debt sustainability analysis. The IMF currently treats the USL as a non-recourse contingent liability because repayment begins only if Ukraine receives reparations; for program purposes, USL budget support is recorded as grants. An enlarged USL 2.0 using the same limited-recourse terms should receive similar treatment, subject to final judgment from IMF staff.
Ukraine’s urgent needs demand action before the year’s end. With European Council meetings scheduled for October and December and G7 finance ministers due to discuss Ukraine on the sidelines of the IMF–World Bank annual meetings in Bangkok in mid-October, leaders must use these opportunities to agree on a viable financing plan that enables Ukraine to fight a common foe and survive as a thriving, democratic European nation.
This is no time for complacency or delay. Having defended the international order and emerged as an increasingly vital contributor to Europe’s security, Ukraine deserves support now more than ever. Its European and G7 partners have the resources to close the war-driven financing gap. What is needed is the political will to deploy them creatively and without delay.
Vladyslav Rashkovan
Alternate Executive Director, International Monetary Fund
Vladyslav Rashkovan is an alternate executive director of the International Monetary Fund and a former deputy governor of the National Bank of Ukraine.
Gregory P. Wilson
Independent Consultant and Author
Gregory P. Wilson is a consultant, author, and former deputy assistant secretary in the U.S. Treasury Department.
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
While the EU and European governments are embracing the much-lauded middle-power moment, this entails three difficult conundrums.
Richard Youngs
Europe is facing rising populism internally as well as external pressures from Russia, China, Turkey, and the United States.
Dimitar Bechev
A notable degree of participative democracy has firmly arrived in Europe. But to have more far-reaching impact, democratic deliberation needs to move into a radically new phase.
Richard Youngs
Much has been said of the changes Brussels is trying to make to the EU enlargement process. Here’s why gradual integration might—or might not—be the answer.
Dimitar Bechev
The European Commissioner for Trade is headed to China. But after President Xi’s bridge-building visit to Washington, can a more isolated EU overcome Beijing’s stranglehold on critical raw materials? Who will blink first?
Rym Momtaz, ed.